One of the most common frustrations I hear comes from people who are, on paper, in great financial shape—and still get told they “don’t make enough” to qualify for a mortgage.
Retirees living comfortably off their savings. Business owners who write off most of their income. People who just sold a company and are between paychecks. On a tax return, their income looks modest. In real life, they have substantial assets and pay their bills without a second thought.
For these buyers, a traditional income-based loan is the wrong tool. An asset depletion loan is often the right one—and a recent change now lets some borrowers use their home equity to help qualify, which wasn’t possible before.
What an Asset Depletion Loan Actually Is
Asset depletion (sometimes called asset-based or asset-utilization qualifying) is a way to qualify for a mortgage using your assets instead of a paycheck.
Here’s the key point most people get wrong: you are not liquidating your accounts or borrowing against them. Nothing is drained. The lender simply looks at your qualifying assets and converts them into a monthly “income” figure on paper, which is then used to see whether you can support the mortgage payment.
It’s a qualifying method—not a withdrawal.
How the Math Works
Most asset depletion programs take your qualifying assets and spread them across a set number of months to create that monthly income figure. A five-year (60-month) schedule is common.
Here’s a simplified example:
Say a borrower has $1,200,000 in qualifying assets. Divide that by 60 months, and it produces $20,000 per month of qualifying income—even if their tax return shows a small fraction of that.
That $20,000 figure is what the lender uses to qualify them, the same way it would use a salary. Suddenly a buyer who was told “no” by a conventional lender is very much a “yes.”
One important nuance: not every asset counts dollar-for-dollar. Cash and bank accounts typically count at or near full value, while investment and retirement accounts are usually discounted to account for market swings and taxes. A good loan officer will show you what your specific mix of assets actually produces before you count on a number.
What’s New: Using Home Equity as a Supplemental Asset
This is the part worth paying attention to.
For years, asset depletion only counted liquid financial assets—bank accounts, brokerage accounts, retirement funds. The equity in your home did nothing to help you qualify, even if it was substantial.
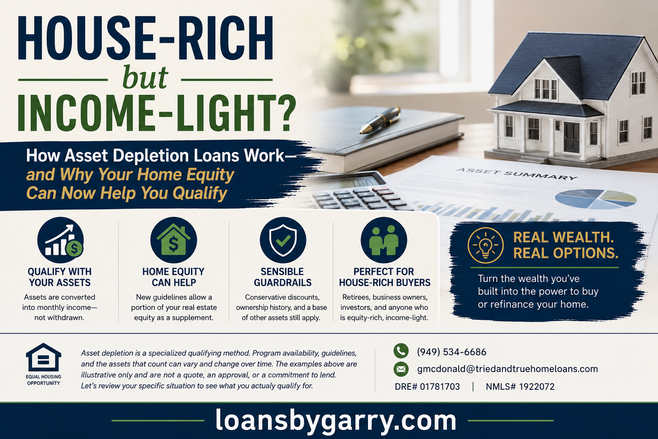
Under newer guidelines, a portion of your real estate equity can now be added to the asset pool as a supplement. For borrowers whose wealth is concentrated in property rather than cash, this can be the difference between qualifying and coming up just short.
There are sensible guardrails around it, and this is exactly why it pays to talk through your situation rather than guess:
- It’s a supplement, not a stand-alone solution—home equity is added on top of other qualifying assets, not used by itself.
- You need meaningful equity in the property, and lenders apply a conservative discount to that equity (they don’t count it dollar-for-dollar).
- The property generally needs a track record of ownership, and its value is confirmed through an approved valuation.
- You’ll still need a base of other qualifying assets alongside it.
The takeaway isn’t the fine print—it’s the headline: home equity that used to sit on the sidelines can now help you qualify.
Who This Really Helps
Asset depletion—especially with the home-equity enhancement—tends to be a great fit for:
- Retirees with strong savings and investments but limited “paycheck” income
- Business owners and self-employed borrowers whose tax returns understate their real financial picture
- Recent sellers—of a business, a property, or a practice—who are asset-rich between income events
- Real estate investors and property owners who hold significant equity but show modest taxable income
- Anyone who is equity-rich and income-light and keeps hearing “no” from conventional lenders
Questions Worth Asking Yourself
- Do I have significant savings, investments, or home equity but modest reportable income?
- Have I been turned down—or expect to be—because my tax returns don’t reflect my real financial strength?
- Am I a retiree or near-retiree who would rather qualify on my assets than on a paycheck I no longer earn?
- Do I own property with substantial equity that I’d like to put to work?
If you answered yes to any of these, asset depletion is worth a conversation.
The Bottom Line
You don’t always need a W-2 or a big taxable income to buy or refinance a home. If you’ve built real wealth—in your accounts, your investments, or your property—there’s very likely a way to turn that into qualifying power.
The home-equity piece is new enough that a lot of borrowers (and even some lenders) don’t realize it’s an option yet. If you’re house-rich but income-light, let’s sit down and run your actual numbers. You may qualify for far more than you’d expect.
Note: Asset depletion is a specialized qualifying method. Program availability, guidelines, and the assets that count can vary and change over time. The examples above are illustrative only and are not a quote, an approval, or a commitment to lend. Let’s review your specific situation to see what you actually qualify for.