A lot of buyers walk into negotiations with one goal:
“Let’s get the seller to lower the price.”
That sounds logical. After all, paying less for a house is a good thing.
But in today’s market, some of the smartest buyers are asking for something completely different:
Seller credits.
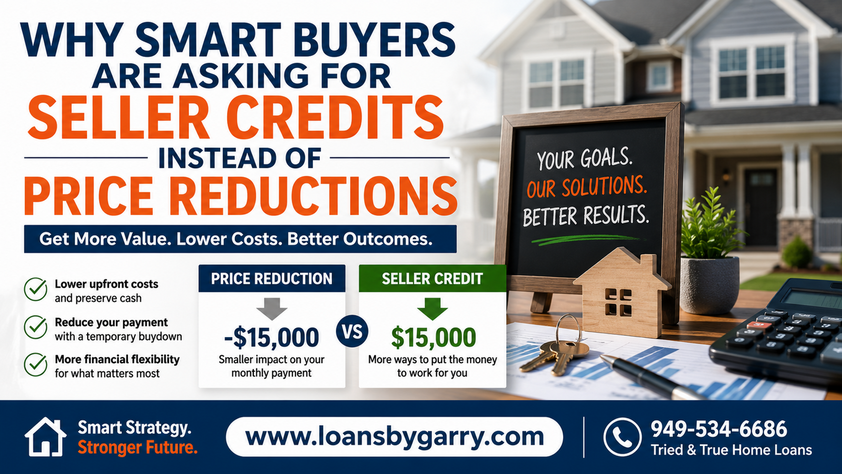
And in many cases, seller credits can provide far more financial benefit than a comparable price reduction.
Let’s look at why.
The Problem Buyers Are Really Trying to Solve
When buyers say they want a lower price, what they’re usually saying is:
“I want a lower payment.”
Those are not necessarily the same thing.
A small reduction in purchase price often has very little impact on the monthly mortgage payment.
What impacts affordability much more is how the money is used.
A Real Example
Let’s say you’re purchasing a home for $800,000.
You negotiate with the seller and they agree to provide $15,000 in value.
You have two options:
Option 1: Price Reduction
The seller lowers the purchase price from $800,000 to $785,000.
Sounds great.
But on a typical mortgage, that $15,000 reduction may only lower the monthly payment by roughly $75 to $100 per month.
Helpful? Absolutely.
Life-changing? Probably not.
Option 2: Seller Credit
Instead of reducing the price, the seller provides a $15,000 credit toward your closing costs, prepaid expenses, or financing strategy.
Now that same $15,000 can potentially be used to:
- Cover closing costs
- Preserve your cash reserves
- Reduce your upfront investment
- Help fund a temporary buydown
In many cases, the impact is significantly greater.
Why Buyers Love Buydowns
One of the most popular uses for seller credits today is a temporary buydown.
For example, a seller credit may be used to create a 2-1 buydown that lowers the buyer’s interest rate during the first two years of the loan.
That can translate into hundreds of dollars per month in savings during the period when buyers are adjusting to homeownership expenses.
Compare that to a small payment reduction from a price cut and it’s easy to see why many buyers prefer credits.
Why Sellers Often Prefer Credits Too
Seller credits can be attractive to sellers as well.
Why?
Because the recorded sales price remains higher.
Instead of publicly reducing the home’s value, the seller contributes toward the buyer’s financing costs.
In many situations, both parties walk away happier.
When a Price Reduction Makes Sense
Price reductions aren’t bad.
There are situations where reducing the purchase price is the right move.
For example:
- The home is significantly overpriced
- The appraisal comes in low
- The buyer is making a large down payment
- Long-term payment reduction is the primary goal
The key is understanding the numbers before negotiating.
Every Situation Is Different
The best negotiation strategy depends on:
- Purchase price
- Loan amount
- Down payment
- Interest rate
- Available seller concessions
- Buyer’s cash reserves
That’s why I encourage buyers to run the numbers before deciding what to ask for.
Sometimes a price reduction wins.
Sometimes seller credits win.
The smart move is knowing which one benefits you the most.
The Bottom Line
Most buyers negotiate based on purchase price.
The smartest buyers negotiate based on outcomes.
In today’s market, seller credits can often create more value than a comparable price reduction.
If you’re buying a home and want to see which strategy makes the most sense for your situation, I’m happy to run the numbers.
Sometimes the best deal isn’t the lowest price—it’s the smartest structure.
Garry McDonald
Loan Officer | Tried & True Home Loans
(949) 534-6686 | gmcdonald@triedandtruehomeloans.com
DRE# 01781703 | NMLS# 1922072